 Bordeaux
 Burgundy
 Champagne
 Rhône
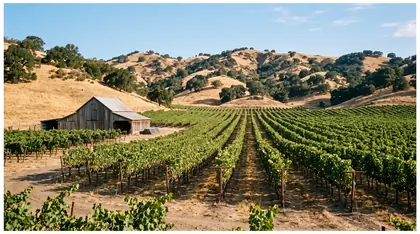 Napa Valley
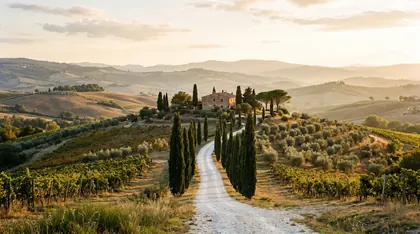 Tuscany
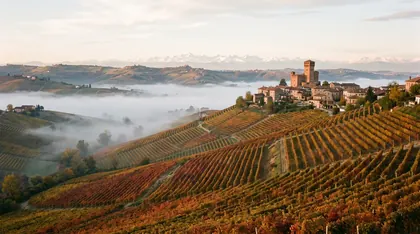 Piedmont
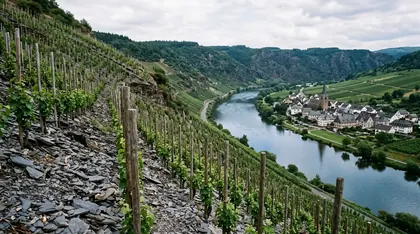 Mosel
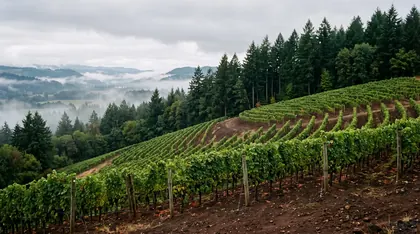 Oregon
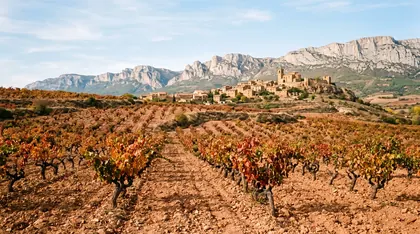 Rioja
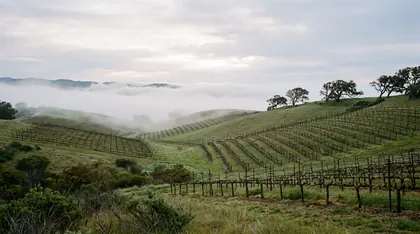 California sparkling
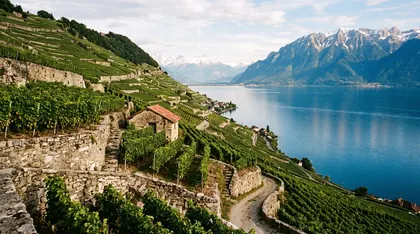 Valais and Lavaux
 England
 Douro
 Etna
 Mendoza
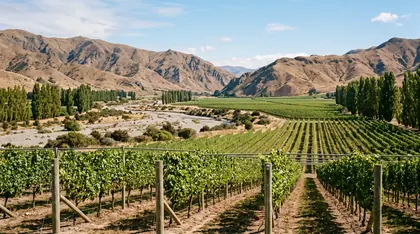 Marlborough
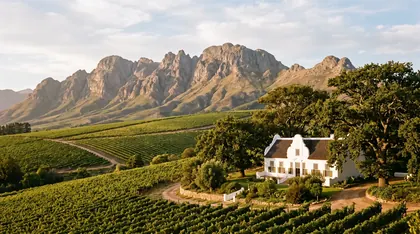 Stellenbosch
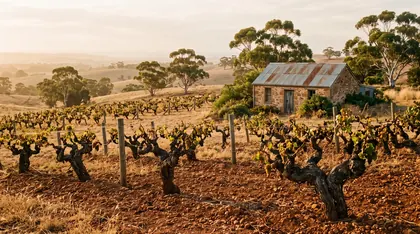 Barossa Valley
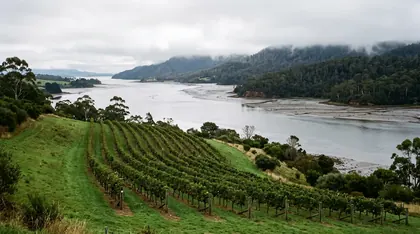 Tasmania
 Beaujolais
 Jura
 Alsace
 Loire
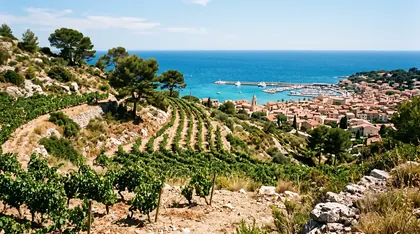 Provence
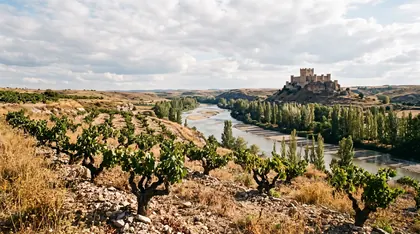 Ribera del Duero
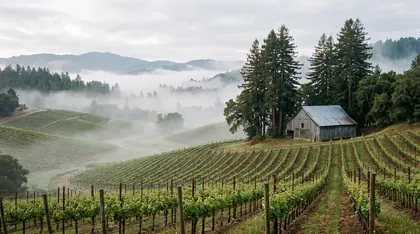 Sonoma
 Was Land kostet
 Gute und schlechte Jahrgänge
 Appellationen
 Berühmte Weinlagen
 Berühmte Weine
 Wer sie herstellt
 Einen Jahrgang finden
 Weine vergleichen
By the end you will be able to
- Calculate a real return by taking inflation away from a nominal return
- Estimate a yearly growth rate (CAGR) from a total gain over several years
- Work out how buying, selling and storage costs shrink a headline gain
- Explain volatility, drawdown and survivorship bias with examples
- Spot the warning signs of a wine investment scam
Nominal, real and compound returns
A return is how much something gained or lost, usually shown as a percentage of what you paid. If a bottle bought for $100 later sells for $200, the total return is 100%. That figure, counted in plain dollars, is the nominal return.
But a dollar buys less every year, because prices in general creep up. That creep is inflation. If everyday prices rose 30% over the same period, part of your bottle's gain was just keeping pace. The real return is what is left after inflation, and it tells you whether you can actually buy more stuff than before. A handy rule for one year: real return is roughly the nominal return minus the inflation rate. If something rises 5% in a year when inflation is 3%, the real return is roughly 2%.
Total returns hide time. A 100% gain in five years is impressive; the same gain over thirty years is not. To compare fairly, we use the compound annual growth rate, or CAGR: the steady yearly rate that would turn the starting value into the ending value. It is compound because each year's growth builds on the last, just as interest in a savings account earns interest of its own.
A quick way to estimate it is the rule of 72: divide 72 by the number of years something took to double, and you get its rough yearly growth rate. Doubling in 10 years is about 7% a year. Doubling in 6 years is about 12% a year. Doubling in 24 years is only about 3% a year, which may barely beat inflation.
Put it together with made-up round numbers. A bottle goes from $100 to $200 in ten years: about 7% a year nominal. If inflation averaged 3% a year, the real return was roughly 4% a year. Still positive, but a long way from the headline doubled.
Remember Always ask over how many years, and after inflation: CAGR turns a total gain into a yearly rate, and the real return takes inflation away.
The costs that eat returns
Price charts of wine usually show the price of the wine, not the experience of owning it. Owners pay costs that charts leave out. Buying can carry a merchant's margin or an auction buyer's premium, commonly in the region of 20% to 25%. Storage and insurance are charged every year. Selling can carry a seller's commission, shipping and paperwork. And there may be tax on any profit.
Here is a made-up case with round numbers. You buy a case for $1,000. Over ten years you pay $30 a year to store and insure it, $300 in all. The market price rises 60%, to $1,600, which sounds great. You sell at auction for a hammer price of $1,600 and pay a 10% seller's commission of $160, so you receive $1,440. Take away the $1,000 you paid and the $300 of storage: your profit is $140.
That is a 14% gain over ten years, or a little over 1% a year, before any tax. If inflation averaged even 2% a year, prices in general rose about 22% over the decade, so in real terms the owner actually lost ground. A headline 60% rise turned into a real loss.
Notice how much depends on the costs at each end. If you had bought that same case at auction, paying a 25% premium, it would have cost $1,250 instead of $1,000, and the whole profit would have disappeared. Costs are certain; future prices are not. That is why careful researchers always ask what a return looks like after every cost, not before.
Remember Buying costs, storage, insurance, selling fees and tax are certain, while price gains are not, and together they can turn a headline gain into a loss.
Volatility, drawdowns, booms and busts
Risk, in money terms, is the chance that things turn out differently from what you hoped, especially worse. Two measures help describe it. Volatility is how much a price jumps around from month to month or year to year. Drawdown is how far a price falls from its highest point before it recovers. A collection that peaks at $10,000 and slides to $7,000 has had a 30% drawdown.
Drawdowns are harder to recover from than they look. After a 50% fall, $1,000 becomes $500, and it now needs to rise 100% just to get back to $1,000. After a 30% fall it needs to rise about 43%.
Fine wine has had dramatic swings. Prices of top Bordeaux climbed steeply into 2011, driven partly by fast-growing demand from buyers in China, then fell for several years. More recently, fine-wine prices rose strongly in 2021 and 2022 and then fell back in 2023 and 2024. Indices such as the Liv-ex Fine Wine 100, which tracks the prices of a basket of widely traded fine wines, show both moves.
Two lessons follow. First, anyone who bought near a peak could wait many years to see their money again, and some never do. Second, wine prices are also less precise than they look, because many wines trade rarely. An index can look calmer than the experience of an owner who actually tries to sell in a falling market. Past performance does not predict the future, in wine as anywhere else.
Remember Volatility is how much prices swing; drawdown is how far they fall from a peak, and big falls need even bigger rises to recover.
Survivorship bias and tax
Survivorship bias is the mistake of looking only at the winners because the losers have disappeared from view. If you only ever hear from people who won the lottery, playing looks like a great idea. Wine has the same trap. The wines in a famous index today are mostly the ones that became famous and kept their value. Wines that were once fashionable and faded, bottles that were damaged, and lots that failed to sell at auction rarely make headlines.
So when someone shows you a chart of a wine that went up tenfold, ask what happened to all the wines that people bought with the same hopes in the same year. A fair picture includes the ones that did badly.
Then there is tax. Rules differ by country, and this course is not tax advice. In the United States, the Internal Revenue Service treats wine held as an investment as a collectible. Under IRS Topic 409, long-term gains on collectibles can be taxed at a maximum federal rate of 28%. That is higher than the top federal rate on long-term gains from most shares, and state taxes may come on top.
Tax matters because it applies to the gain, after the costs you can count. In a good case, tax takes a slice of the profit. In a weak case like the one in the last lesson, there may be little profit to tax at all. Either way, a return before tax is not the money you keep.
Remember Look for the losers that charts leave out, and remember that in the US, gains on collectibles can be taxed at up to 28% federally.
How to spot a wine investment scam
Wine has attracted investment scams for decades, and regulators in several countries have warned about them. In many places, wine is not a regulated investment, so the protections people expect from a bank or a fund may simply not apply. The pattern is familiar enough to learn.
Warning signs to recognise:
An unexpected call or message from a company you have never contacted, offering to make you money. Promises of high or guaranteed returns, often with smooth charts of the past. No honest seller can guarantee what a wine will be worth. Pressure to decide fast, because the offer will close today. Prices well above what the same wine sells for elsewhere, which you can check against merchants and auction results. Wine you never see: it is said to be in a warehouse, but you cannot get a statement from the warehouse in your own name or arrange delivery. Requests to pay more fees before you can sell or collect.
A cruel second wave often follows. People who lost money are contacted by a firm offering to recover it, for a fee. These recovery offers are frequently scams by the same groups.
Good habits protect anyone. Check prices independently. Confirm with the warehouse directly that wine is held in your name. Look up a firm on official warning lists, such as the US Securities and Exchange Commission's investor education site or the UK Financial Conduct Authority's ScamSmart pages. Never let a stranger rush you. If something sounds too good to be true, it almost always is.
Remember Cold contact, guaranteed returns, pressure, inflated prices and wine you can never verify or collect are the classic signs of a wine scam.
Test your knowledge
Ten questions. Pick an answer to see whether it is right and why. Your best score is kept in this browser only.
Research and education only. Nothing here is investment advice.
More courses
-
 Beginner · Über 18 minutes · 5 lessons · 10 questions
Fine wine collecting 101
Why a tiny share of the world's wine becomes something people collect, how supply and demand work when no more bottles can ever be made, and how collectors actually get hold of them.
-
 Intermediate · Über 18 minutes · 5 lessons · 10 questions
Auctions, storage and fakes
What a bottle really costs at auction, why the price you can sell at is lower than the price you can buy at, and how storage, provenance and counterfeits decide what a bottle is worth.
-
 Beginner · Über 18 minutes · 5 lessons · 10 questions
Wine production economics 101
How a winery makes, or loses, money: revenue, cost and profit, fixed and variable costs, the price of land, what yields mean, and the long chain from vine to glass.