 Bordeaux
 Burgundy
 Champagne
 Rhône
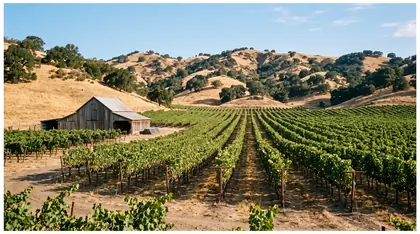 Napa Valley
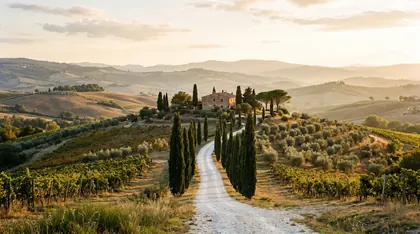 Tuscany
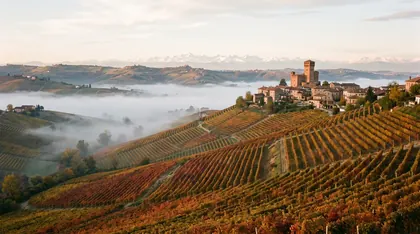 Piedmont
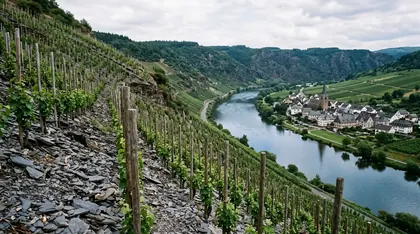 Mosel
 Oregon
 Rioja
 California sparkling
 Valais and Lavaux
 England
 Douro
 Etna
 Mendoza
 Marlborough
 Stellenbosch
 Barossa Valley
 Tasmania
 Beaujolais
 Jura
 Alsace
 Loire
 Provence
 Ribera del Duero
 Sonoma
 Was Land kostet
 Gute und schlechte Jahrgänge
 Appellationen
 Berühmte Weinlagen
 Berühmte Weine
 Wer sie herstellt
 Einen Jahrgang finden
 Weine vergleichen
Wie eine Weinauktion funktioniert
Auction houses such as Christie's, Sotheby's and Hart Davis Hart sell wine on behalf of owners. Before a sale the house checks the bottles, describes their condition in a catalogue, and groups them into lots, such as a single bottle or a case of twelve. Many lots have a reserve, a secret minimum below which the seller will not sell.
On the day, bidders compete in the room, by phone or online. The price rises until only one bidder is left. When the auctioneer brings down the gavel, that last bid is the hammer price. If bidding never reaches the reserve, the lot goes unsold.
Buyer's premium and seller's commission
The hammer price is not what the buyer pays. Auction houses add a buyer's premium, a fee charged as a percentage of the hammer price. For wine it is commonly in the region of 20% to 25%. On top of that the buyer may owe sales tax and shipping.
The seller pays too. The house takes a seller's commission, also a percentage of the hammer price, and may charge for insurance or photography. Commissions are often negotiated, and big sellers usually pay less. So the auction house earns money from both sides of the same sale.
Estimates, reserves and the winner's curse
Before each sale the auction house publishes an estimate for every lot, such as "$800 to $1,200". It is the house's informed guess at what the lot will fetch, based on recent sales of the same wine and its condition. Estimates help bidders, but they are also a sales tool: a low estimate can attract more bidders and spark competition.
The final price depends on who turns up. An auction does not discover what a wine is worth to everyone; it discovers what it is worth to the two keenest bidders in the room that day. If two determined collectors both want a bottle for a special anniversary, the price can soar far above the estimate. If they are both away, the same bottle might sell near the bottom of the range, or not at all.
Economists have a name for one trap here: the winner's curse. When many people bid for something whose true value is uncertain, the person who wins is often the one who guessed the value highest of all, and so is the most likely to have paid too much. Excitement in the room makes this worse. Experienced bidders protect themselves by deciding their maximum before the sale and sticking to it.
For anyone studying prices, this means a single auction result is a noisy clue. A pattern of results for the same wine, across many sales, tells you far more than one record-breaking night.
Bid, ask and the spread
Outside auctions, wine also trades on exchanges and between merchants. There, prices are quoted as a bid, the highest price any buyer is currently offering, and an ask, the lowest price any seller will accept. The gap between them is the spread.
If the best bid for a case is $950 and the best ask is $1,050, the spread is $100. Someone who buys at the ask and immediately needs to sell at the bid loses $100 straight away. A narrow spread is a sign that lots of people are trading; a wide one means buyers and sellers are far apart.
Think about it: a used-car dealer offers you $8,000 for your car but sells the same model for $10,000. What is the spread, and why does the dealer need it?
Liquidity: how quickly you can sell
Liquidity means how quickly and cheaply you can turn something into cash without cutting the price. Money in a bank account is very liquid. A house is not: selling it takes months and costs fees.
Fine wine sits towards the illiquid end. Even famous wines may need weeks to sell, an auction may only be held every month or two, and a seller in a hurry may have to accept a lower price. Lesser-known wines can be much harder still. Liquidity is one of the biggest hidden costs of owning wine as an asset.
Why the price you pay and the price you could sell for differ
Put fees and spreads together and you get the round-trip cost: the total cost of buying something and later selling it again. For wine bought and sold at auction, the round trip can easily swallow a quarter or more of the money involved.
That is why the prices you read in auction headlines are not the same as what an owner would receive. A record hammer price tells you what one buyer was willing to bid on one day. The buyer then paid more than that, and a future seller of the same bottle would receive less.
Before treating any auction result as "the value" of a wine, it helps to ask three questions:
- Is this the hammer price, or the price including the buyer's premium?
- How much would a seller actually receive after commission?
- How many similar bottles have sold recently, and at what prices?
Worked example: the round trip at auction
Here is a made-up bottle with round numbers. The buyer's premium is 25% and, years later, the seller's commission is 10%. Tax, shipping and storage are left out to keep it simple.
| Hammer price when bought | $1,000 |
|---|---|
| Buyer's premium (25% of $1,000) | $250 |
| Total the buyer pays | $1,250 |
| Hammer price when sold later (no change) | $1,000 |
| Seller's commission (10% of $1,000) | $100 |
| Money the seller receives | $900 |
| Round-trip cost | $1,250 minus $900 = $350, which is 28% of $1,250 |
| Hammer price needed just to get $1,250 back | $1,250 ÷ 0.9 = about $1,389 |
With no change in the market price, the owner loses $350. The hammer price would have to rise by about 39%, from $1,000 to about $1,389, just to break even, before counting storage, insurance or the interest the money could have earned elsewhere.
Key words
- Hammer price
- The winning bid at an auction when the gavel falls, before fees.
- Buyer's premium
- A fee the buyer pays the auction house on top of the hammer price, commonly in the region of 20% to 25% for wine.
- Seller's commission
- A fee the auction house takes from the seller, as a percentage of the hammer price.
- Bid and ask
- The highest price a buyer is offering and the lowest price a seller will accept.
- Spread
- The gap between the bid and the ask.
- Liquidität
- How quickly and cheaply something can be turned into cash without lowering the price.
- Round-trip cost
- The total cost of buying something and later selling it again.
Check your understanding
A bottle sells at a hammer price of $2,000 with a 20% buyer's premium. What does the buyer pay?
Show the answer
$2,000 plus 20% of $2,000 ($400) = $2,400, before tax and shipping.
Why is fine wine described as fairly illiquid?
Show the answer
Because selling it takes time, auctions are not held every day, and a seller in a hurry may have to accept a lower price, while fees eat into what they receive.
The best bid for a case is $1,800 and the best ask is $2,000. What is the spread?
Show the answer
$2,000 minus $1,800 = $200.
Why is an auction headline price not the same as what an owner could get for the same wine?
Show the answer
The headline may include the buyer's premium, and a seller would also pay commission, so the seller would receive noticeably less than the headline figure.
Go deeper on Corkonomics
Sources and further reading
- Wine auction results Christie's
- Wine auction results Sotheby's
- Wine auction results Hart Davis Hart
Research and education only. Nothing here is investment advice.
Next chapterStorage, condition and provenance← Previous chapterAll chapters