CorkonomicsThe economics of wine production, collection, and vineyards
Les chiffres
Les terres de vignoble · Pauillac≈$2,798,250 un hectare▼ en baisse 17% on 20232024Prix d'ouverture · Château Lafite Rothschild 2025≈$376 une bouteille▲ en hausse 17% sur l'année précédenteVendu aux enchères · Romanée-Conti Grand Cru, DRC 2019$22,917 une bouteilleSotheby's, Sep 2026Coût de fabrication d'une bouteille · Burgundy grand cru (Pinot Noir)$48–283Droits de douane américains sur les vins de · Canada+50%depuis Aug 2026Bouteille du quotidien dans un magasin américain$13.77 un litre▼ en baisse 1.3% en un anSep 2026Les terres de vignoble · Margaux≈$1,567,020 un hectare▼ en baisse 7% on 20232024Prix d'ouverture · Château Cheval Blanc 2025≈$376 une bouteille▲ en hausse 22% sur l'année précédenteVendu aux enchères · La Tâche Grand Cru, DRC 2018$5,417 une bouteilleSotheby's, Sep 2026Coût de fabrication d'une bouteille · Champagne prestige cuvée$26–89Droits de douane américains sur les vins de · Australia+12.5%depuis Jul 2026Les terres de vignoble · Côte-Rôtie≈$1,511,055 un hectare▲ en hausse 8% on 20232024Prix d'ouverture · Château Mouton Rothschild 2025≈$336 une bouteille▲ en hausse 19% sur l'année précédenteVendu aux enchères · Richebourg Grand Cru, DRC 2012$3,542 une bouteilleSotheby's, Sep 2026Coût de fabrication d'une bouteille · Bordeaux classified growth (2nd–5th)$17–61Droits de douane américains sur les vins de · New Zealand+12.5%depuis Jul 2026Les terres de vignoble · Côte de Nuits grand cru≈$7,275,450 un hectare2019Prix d'ouverture · Château Palmer 2025≈$268 une bouteille▼ en baisse 19% sur l'année précédenteLes terres de vignoble · Pomerol≈$2,238,600 un hectare2023
Corkonomics
ApprendreCépagesRégionsVinsActualités
Les bases du vinLes cinq types de vinComment déguster le vinComment lire une étiquette de vinLe vin et la nourritureMots du vin
Learn the economicsThe economics of wine productionThe economics of wine collectingCourses
Régions
Vins
PrixCe que coûte la fabrication d'une bouteilleCe que coûte le terrain viticoleCe que rapportent les raisinsCe que la frontière ajoutePourquoi le vin coûte ce qu'il coûtePrix de mise en marchéRésultats de ventes aux enchèresDroits de douaneVue d'ensemble du marchéLe vin dans les statistiques officiellesÉconomie du vignobleRecherche
PlusInterroger les donnéesAgents IAEnregistréAPIÀ proposMéthodologieContact
Mode sombre
Langue
Currency
Paramètres
Mode sombre
Langue
Currency

Vous débutez dans le vin ? Commencez par les leçons courtes, puis cherchez tout mot que vous ne connaissez pas.

Apprendre · Mots du vin · Vos pages sauvegardées

How wine distribution margins work

From the château gate to the shelf: the négociant, the importer, the distributor and the retailer each take a margin, and together they can double the price.

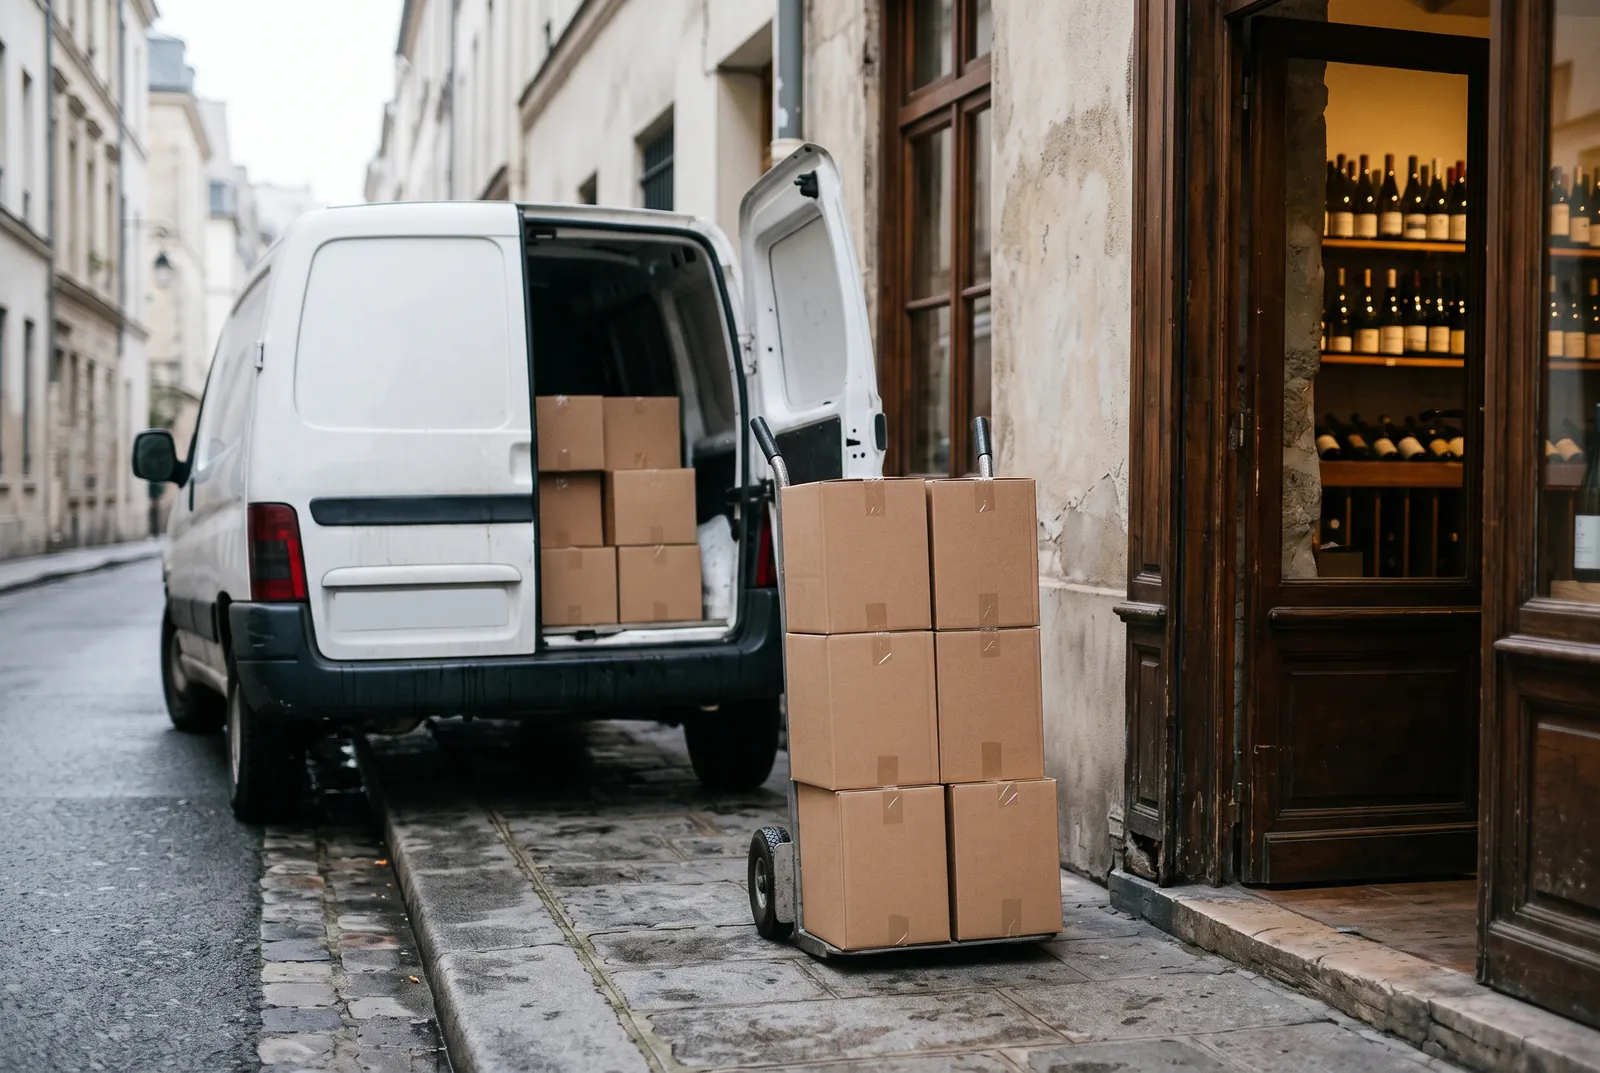
Boxes of wine on a sack truck outside a wine shop, with a delivery van behind

Publié 3 September 2026 · Révisé September 2026 · Corkonomics éditorial ·

Between the winery and the glass sit two to four businesses, each with a margin. In Bordeaux a négociant adds 10–20% and a courtier 2%; an importer and retailer then add their own. In the United States the three-tier system commonly doubles the winery price by the time a bottle reaches a shelf. The cult estates that sell direct keep all of it.

The Place de Bordeaux

A classified growth sells to a négociant through a courtier (broker). The courtier takes about 2%; the négociant takes 10–20% depending on the wine's desirability — for the first growths in a hot campaign, less; for an unloved fifth growth, more. The négociant sells to importers and merchants worldwide, who add their own margin. The château sees only its ex-château release price; everything above it belongs to the chain, which is why a château cares so much about where the secondary market sits relative to its release.
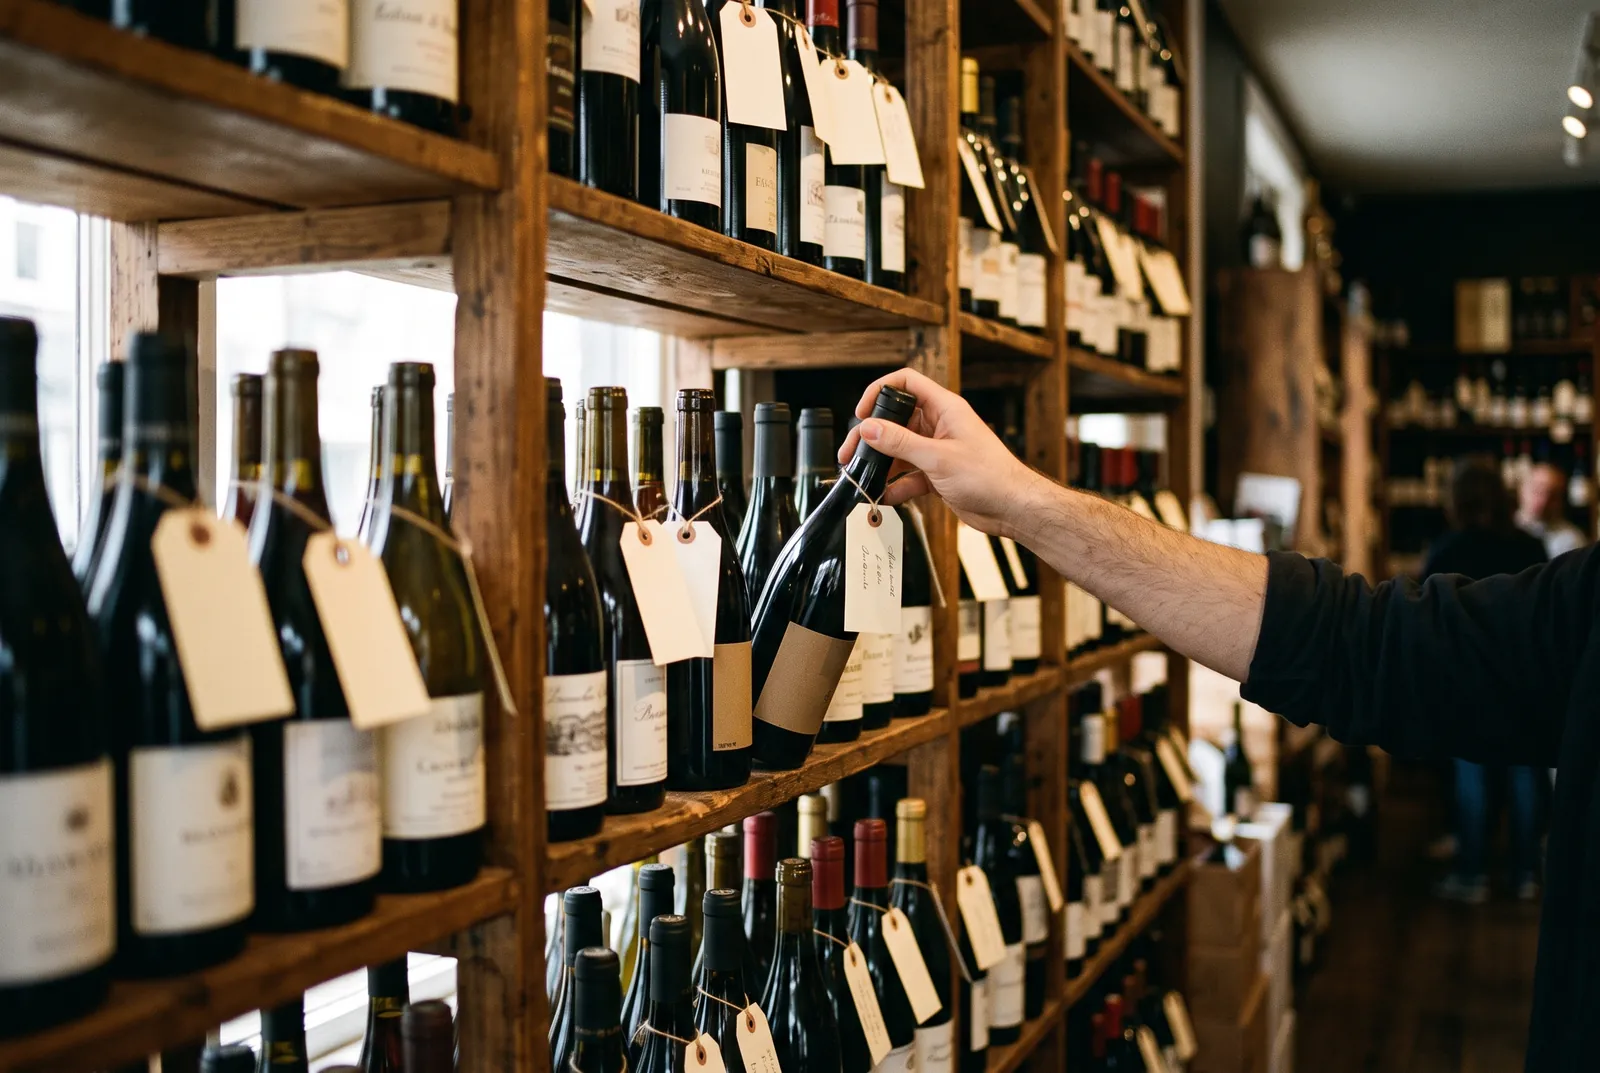
Une main qui prend une bouteille sur un rayon

Three tiers in the United States

Post-Prohibition law requires most wine to pass from producer to distributor to retailer. Distributors commonly work on 25–30% gross margin and retailers on 30–50% on their cost, so a $50 winery price is $65–70 to the retailer and $90–105 on the shelf. Restaurants mark up two to three times. Direct-to-consumer sales — mailing lists, tasting rooms, wine clubs — bypass all of it, and are the reason Napa's cult estates can release at $500 and keep $500.

Allocation and the secondary market

Where release prices sit far below market — Burgundy, cult Napa — the largest margin is not a distributor's but the allocation holder's: the difference between the release price and the auction price, captured by whoever had the right to buy. This is the economics of the waiting list.
Un serveur qui verse une petite dégustation de vin rouge à une table de restaurant

What it means for value

A collector's 'return' is measured from the price paid, which includes every margin above; a wine bought at retail must appreciate by the retail margin before the buyer is even. It is one reason the gross index return on the benchmarks page is not a return anyone earns.

Négociant margin
10–20% of ex-château; courtier ≈ 2%Trade reporting on the Place de Bordeaux
US three-tier
Distributor ≈ 25–30%; retailer ≈ 30–50% on costIndustry references

Sources

  1. How the Place de Bordeaux works, Liv-ex, 2024. Récupéré 3 September 2026.
Dernière révision: September 2026Signaler une erreur sur cette page